Delhi High Court Bars Commercial Banks from Unilaterally Cutting Interest on Court-Mandated Fixed Deposits
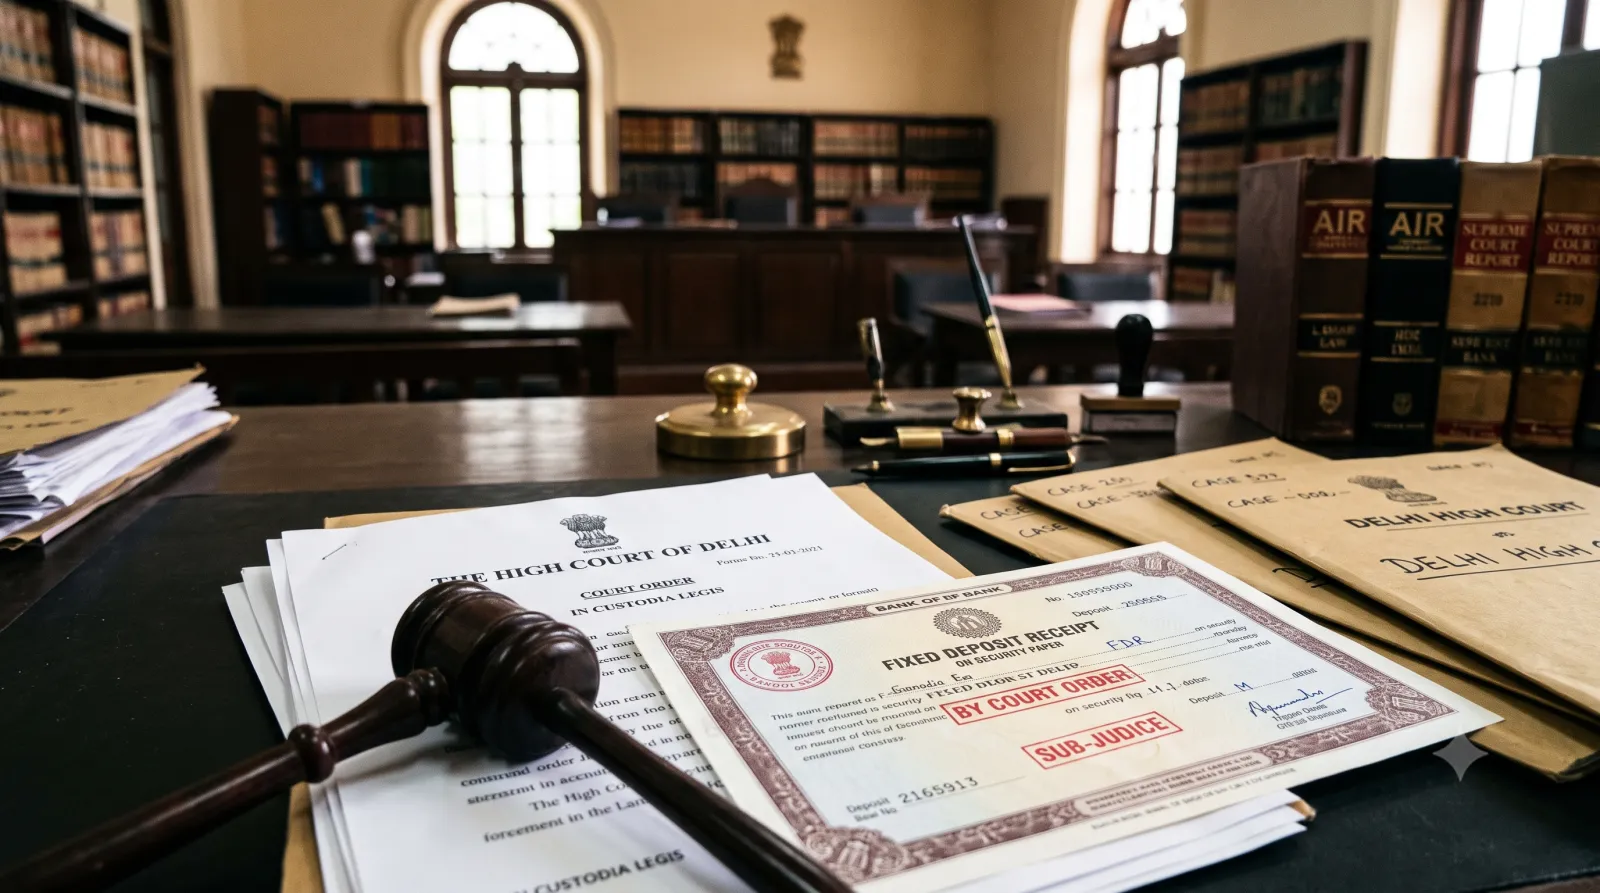
The Delhi High Court has held that commercial banks cannot unilaterally reduce the interest rate on fixed deposits created and maintained under judicial orders. Addressing the administrative handling of litigation deposits, the court made it clear that financial institutions hold such funds in a fiduciary capacity under the superintendence of the judiciary. Once fixed deposit receipts (FDRs) are opened at a specified interest rate pursuant to a court directive, the lender cannot subsequently alter the agreed financial return by relying on internal circulars or general macroeconomic policy changes without first seeking express permission from the court.
Legal Topic
Area of Law: Banking and Commercial Law
Sub-topic: Court Deposits / Fiduciary Duties of Banks
Core Legal Issue
The central question before the court was whether a commercial bank holding fixed deposits created under a judicial directive has the authority to unilaterally slash or recalculate the agreed interest rate during the deposit's tenure.
The court examined whether internal bank guidelines, revised repo rates, or general regulatory circulars issued by the Reserve Bank of India can supersede judicial mandates governing funds held in custodia legis, without the bank moving an application before the court for modification or clarification.
What Did the Court Decide?
The High Court ruled against the bank, holding that any unilateral downward revision of interest on court-directed deposits is legally invalid. The court directed the financial institution to restore the contracted interest rate and make good the shortfall by crediting the deducted earnings back into the deposit account.
The bench observed that court-ordered deposits are fundamentally distinct from ordinary commercial transactions entered into with regular retail customers. Because the funds remain subject to the control and protection of the judiciary, the bank acts as an entrusted custodian rather than a purely commercial counterparty. Consequently, the High Court held that if a bank considers it commercially impracticable to continue honouring the original rate, its only lawful recourse is to approach the court and seek appropriate relief or directions.
Key Legal Points
-
Status as Custodia Legis: Funds deposited under judicial orders are in the custody of the law, placing a heightened fiduciary obligation upon the depository bank.
-
Internal Circulars Subordinate to Court Orders: Internal bank policies, asset-liability adjustments, and general advisory circulars cannot supersede judicial directions or alter court-sanctioned terms.
-
Mandatory Judicial Recourse: A bank wishing to vary, reduce, or recalibrate interest rates on deposits created under court orders must move an application before the concerned bench; it cannot implement changes unilaterally.
-
Restoration of Deductions: Any deficit resulting from an unauthorised mid-tenure rate cut must be promptly restored and credited back by the depository bank.
Relevant Law
-
Banking Regulation Act, 1949: Regulatory framework governing the acceptance of deposits and interest rate compliance by commercial banking entities.
-
Indian Contract Act, 1872 (Section 62): Core contractual principles governing modification and novation, which bar one party from unilaterally varying agreed terms without mutual consent or judicial sanction.
-
Doctrine of Custodia Legis: The established legal principle under which property held under judicial directions remains sheltered from unilateral third-party administrative interference.
Arguments of the Parties
Applicant / Depositor
The applicant argued that the funds were deposited in the bank strictly in compliance with explicit court orders, with the agreed interest rate forming an integral term of the deposit. It was contended that the bank acted arbitrarily and without jurisdiction by reducing the rate of return mid-course, thereby eating into funds earmarked for eventual release to the successful litigant.
Respondent / Bank
The bank submitted that the interest rate revision was neither arbitrary nor punitive, but rather a direct operational implementation of revised banking policies and Reserve Bank of India guidelines. The institution contended that market rate fluctuations and internal guidelines governing term deposits legally entitled it to align existing accounts with prevailing monetary realities.
Why Does It Matter?
This ruling directly impacts an enormous volume of funds locked in Indian courts, including motor accident claims, land acquisition awards, commercial security deposits, and matrimonial settlements. These funds routinely remain with authorised public and private sector banks for years while litigation winds its way through the system.
If lenders were permitted to dilute interest yields at their own discretion whenever central rates fell, vulnerable beneficiaries and litigants would suffer severe losses on funds that they were compelled by law to deposit. For compliance and legal departments of commercial banks, the decision establishes a strict operating procedure: court-mandated fixed deposits cannot be bundled with ordinary retail portfolios for automated rate cuts.
Legal Takeaway
When a commercial bank accepts deposits placed under judicial directions, it acts as a court-supervised custodian and is bound to honour the contracted interest rate. Banks cannot alter or lower returns on these deposits unilaterally, and any change to the financial terms requires prior approval from the court.
Sources
Primary Source:
High Court of Delhi judgment/order addressing unilateral interest rate reductions on court-directed fixed deposit receipts.
Additional Sources:
Bar and Bench reporting on the Delhi High Court litigation; Banking Regulation Act, 1949; Reserve Bank of India Master Directions on Deposit Interest Rates.