Director Cannot Challenge I-T Search Against Company In Personal Capacity: Karnataka High Court
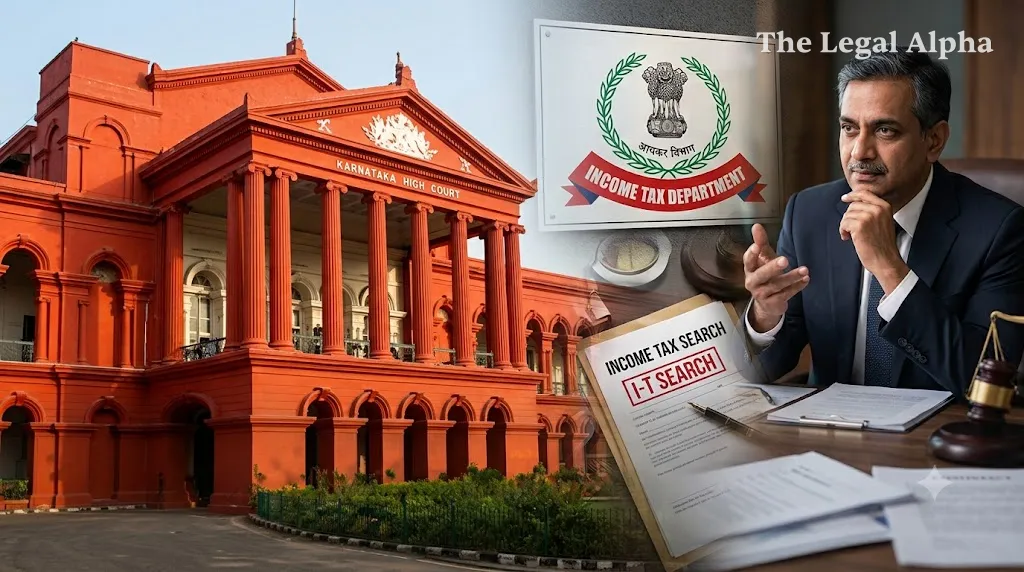
Court: High Court of Karnataka at Bengaluru
Bench: Justice B.M. Shyam Prasad
Date of Pronouncement: October 06, 2026 | Reported: October 08, 2026 (LiveLawBiz ID: 553709)
Subject: Income Tax Act (Section 132 & Section 131) | Search & Seizure / Director Locus Standi
Category
Judgements | Direct Taxation & Corporate Law
The petitioner, Obedulla A, is a director of Attica Gold Private Limited, a company incorporated under the Companies Act and engaged in the gold trade business. The Directorate of Income Tax (Investigation), Bengaluru, conducted search and seizure operations under Section 132 of the Income Tax Act, 1961 against the corporate entity Attica Gold Private Limited. The search warrant and authorizations were issued specifically in the name of the company to investigate alleged tax evasion, unexplained cash movements, and undisclosed assets.
In the course of the post-search investigation, the tax authorities issued statutory summons dated September 30, 2026 under Section 131(1A) of the Act to Obedulla A in his capacity as a director, requiring his personal appearance and production of books of account and explanations regarding the company's financial affairs.
Instead of appearing, Obedulla A approached the High Court of Karnataka by filing a writ petition under Article 226 of the Constitution in his personal, individual capacity. He challenged the constitutional and statutory validity of the search and seizure operations conducted against Attica Gold Private Limited, seeking quashing of the search authorizations and consequential summons. He contended that the statutory conditions precedent for conducting a search under Section 132(1)—such as failure to comply with notices or reasons to believe that undisclosed assets were secreted—were completely absent. The Revenue contested the petition's maintainability, asserting that the search was directed exclusively against the juristic corporate entity, and an individual director has no personal locus standi to challenge a corporate search.
Legal Topic
Direct Taxation & Corporate Jurisprudence – Section 132, Income Tax Act, 1961 (Search and Seizure); Section 131(1A) (Power Regarding Production of Evidence and Investigation Summons); Doctrine of Separate Juristic Personality (Corporate Entity vs. Individual Directors); Locus Standi under Article 226 of the Constitution; Judicial Review of Search Authorizations.
Core Legal Issue
Whether an individual director possesses the legal standing (locus standi) to institute a writ petition challenging an Income Tax search and seizure operation conducted under Section 132 against a private limited company, when the search warrant and authorization are not directed against the director in their personal capacity.
What Did the Court / Authority Decide?
A Single Judge Bench of the High Court of Karnataka at Bengaluru, presided over by Justice B.M. Shyam Prasad, dismissed the challenge to the search authorizations and disposed of the writ petition, upholding the Revenue's preliminary objection that an individual director cannot challenge an income-tax search conducted against a corporate entity.
Justice B.M. Shyam Prasad held that under established company law and direct tax jurisprudence, a company is an independent juristic person distinct from its directors and shareholders. The Court observed that if any person could have a legal grievance concerning the search and seizure or the manner of its authorization under Section 132, such grievance has to be raised by the specific entity affected by the search. Because the search was authorized and executed against Attica Gold Private Limited and not against Obedulla A personally, he lacked locus standi to assail the corporate search in his individual capacity. However, upon the petitioner’s request for reasonable time to respond to the summons, and with the Revenue's consent, the Court permitted him to appear before the investigating authorities on October 14, 2026 in response to the summons dated September 30, 2026, clarifying that failure to appear would leave authorities free to take all measures permissible under law.
Key Legal Points
- Separate Juristic Identity Bars Personal Writ: Justice B.M. Shyam Prasad affirmed that an incorporated company is an independent legal entity. An individual director cannot maintain a writ petition in their personal capacity to challenge a Section 132 search directed solely against the corporate body.
- Grievance Must Be Raised by the Searched Entity: The High Court held that any legal challenge concerning the validity, bona fides, or statutory preconditions of a search authorization under Section 132 can only be instituted by the entity named in the warrant of authorization.
- Summons to Director Does Not Create Cause of Action Against Search: The Bench noted that receiving an investigation summons under Section 131(1A) to testify regarding corporate transactions does not equate to being personally searched under Section 132, nor does it bestow locus standi to impeach the corporate search.
- Strict Obligation to Comply with Section 131 Summons: The Court underscored that corporate directors are statutorily obligated to cooperate with investigation summonses issued under the Income Tax Act.
- Conditional Extension to Appear: The High Court granted an extension permitting the director to appear before the tax authorities on October 14, 2026, warning that default would trigger coercive statutory consequences.
Relevant Law
- Section 132, Income Tax Act, 1961: Vests comprehensive powers of search and seizure in authorized income-tax authorities upon satisfaction of statutory reasons to believe regarding undisclosed income or property.
- Section 131(1A), Income Tax Act, 1961: Empowers the Director General, Principal Director, or authorized investigating officers to summon witnesses, examine persons on oath, and compel production of accounts and records.
- Article 226, Constitution of India: Confers extraordinary writ jurisdiction upon High Courts, which requires the petitioner to demonstrate a direct personal legal injury or violation of a legal right (locus standi).
- Solomon v. Solomon & Co. Ltd. [1897] AC 22 (HL) & Bacha F. Guzdar v. CIT (1955) 27 ITR 1 (SC): Foundational company law authorities establishing the distinct legal personality of a corporation separate from its shareholders and directors.
- Director General of Income Tax (Investigation) v. Spacewood Furnishers Pvt. Ltd. (2015) 12 SCC 179: Landmark Supreme Court precedent defining the narrow parameters of judicial review over the 'reason to believe' recorded for issuing search warrants under Section 132.
Arguments of the Parties
- Contentions of the Petitioner (Obedulla A):
- Represented by Advocate Mohammed Tahir, the petitioner submitted that the search authorization issued by the tax department under Section 132 was arbitrary and lacked the mandatory statutory foundations.
- Counsel argued that there was no failure to comply with prior notices and no credible material existed to form a bona fide 'reason to believe' that undisclosed assets or books were secreted.
- It was contended that as a principal director responsible for the company's governance and facing Section 131(1A) summons, the petitioner was directly affected and possessed standing to challenge the search.
- Contentions of the Respondent (Income Tax Department / Revenue):
- Represented by Additional Solicitor General of India (ASG) Aravind Kamath, assisted by Advocates Y.V. Raviraj and M. Dilip, the Revenue argued that the writ petition was not maintainable at the threshold.
- The ASG submitted that the search warrant was issued against the juristic person, Attica Gold Private Limited, and not against Obedulla A in his personal capacity.
- Counsel maintained that a director cannot conflate their individual identity with the corporate entity to challenge statutory searches, and that the petitioner was merely summoned as a witness to explain company transactions.
Why Does It Matter?
In direct tax enforcement, promoters, directors, and major shareholders routinely attempt to stall corporate tax investigations by filing individual writ petitions in High Courts. When an investigation wing raids a corporation, individual executives frequently seek ad-interim stays against search warrants, alleging lack of statutory reasons to believe while shielding the company behind procedural litigation.
The Karnataka High Court’s ruling in Obedulla A delivers crucial clarity on the doctrine of corporate locus standi in tax raids. By ruling that an individual director cannot challenge an income-tax search against a company in personal capacity, Justice B.M. Shyam Prasad reinforces the foundational corporate law principle that the company alone can assert grievances regarding actions taken against it. The judgment prevents corporate directors from using individual writ petitions as procedural roadblocks to derail Section 132 search investigations and Section 131(1A) inquiries, ensuring that tax authorities can enforce corporate accountability and summon corporate officers without unauthorized judicial obstruction.
Legal Takeaway
An individual director has no locus standi to challenge an Income Tax search and seizure conducted under Section 132 of the Income Tax Act, 1961 against a company in their individual capacity, where the search warrant is directed strictly against the corporate entity. A company possesses an independent juristic personality, and any grievance regarding the validity or authorization of a search must be agitated exclusively by the company itself. Receiving investigation summons under Section 131(1A) does not confer standing upon a director to question the corporate search.
Sources (Primary & Additional)
- Primary Judicial Order: High Court of Karnataka at Bengaluru, Obedulla A v. Income Tax Department & Ors. [Writ Petition disposed of on October 06, 2026], per Justice B.M. Shyam Prasad. High Court of Karnataka Case Management System / LiveLawBiz.
- Authoritative Legal Reporting (LiveLawBiz): Mehak Dhiman, \"Director Can't Challenge Income-Tax Search Against Company In Individual Capacity: Karnataka High Court\" (Article ID: 553709, Published on October 08, 2026). LiveLawBiz Article.
- Direct Tax News Intelligence: Legal Desk, \"Karnataka High Court Affirms Corporate Entity Boundary: Directors Cannot Assail Section 132 Search Warrants in Individual Writs\" (Published on October 08, 2026). Supreme Court & High Court Business Law Judgments - LiveLawBiz.