Bombay High Court Strips Down ₹329-Crore Tax Assessment Against Grasim, Clarifies Scope of 'Deemed Gift' Rules in Rights Offerings
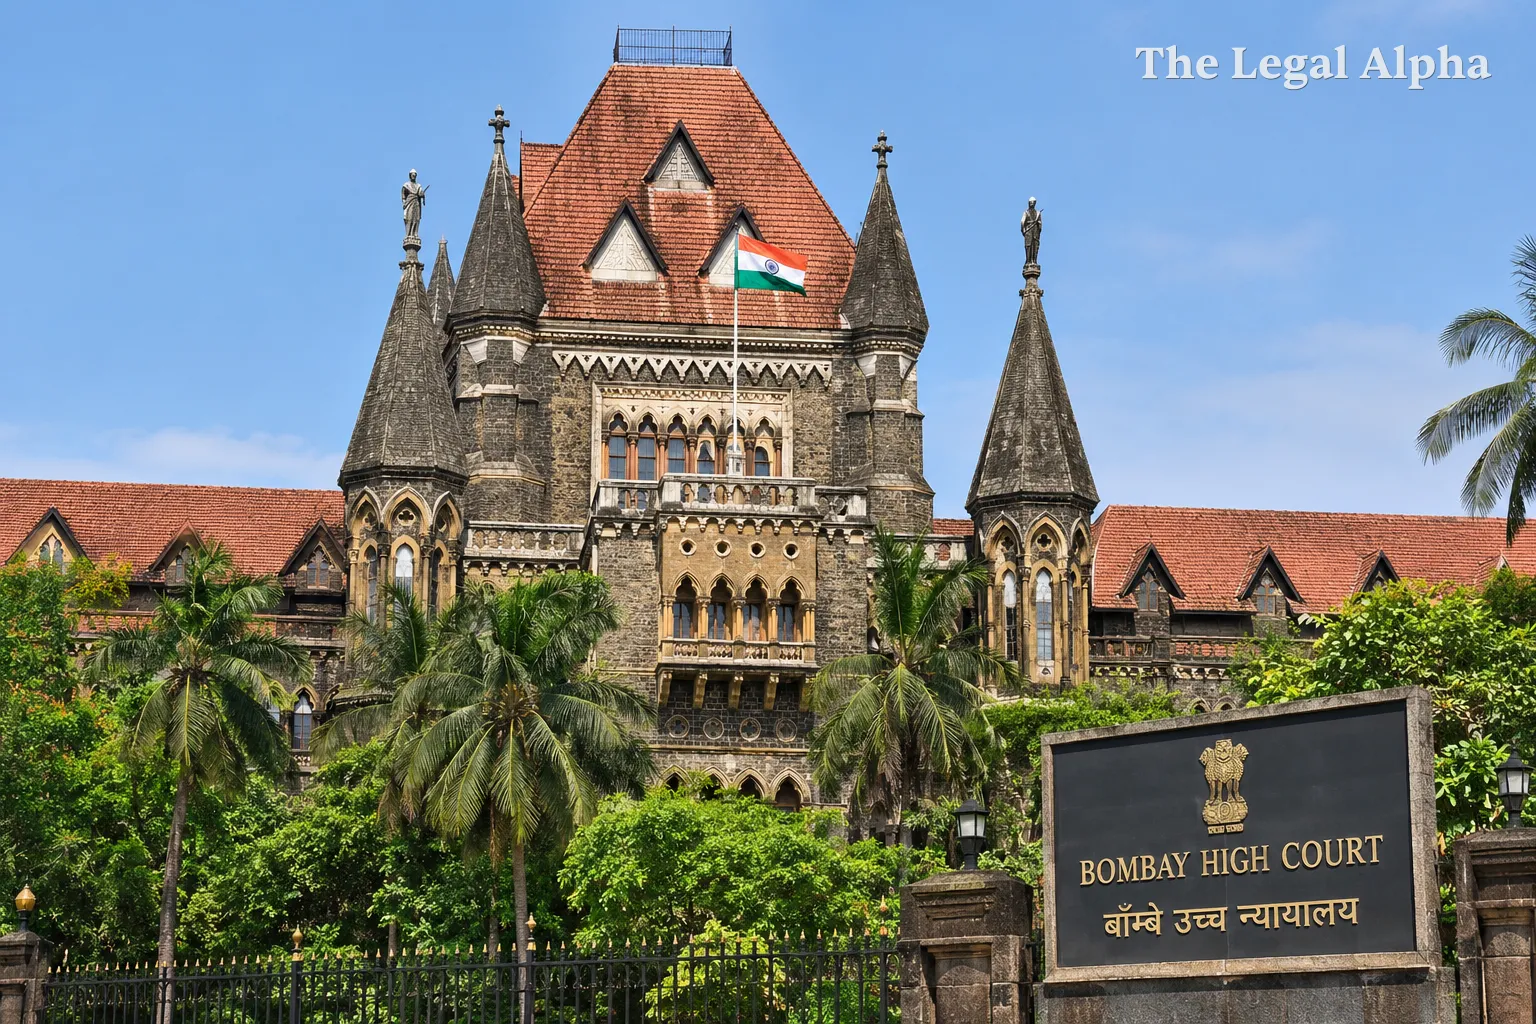
The Bombay High Court set aside an income tax assessment and a related demand of approximately ₹329.04 crore raised against Grasim Industries Limited. The dispute originated from Grasim’s participation in a rights issue floated by telecom operator Vodafone Idea Limited during the 2019–20 financial year (FY20). Grasim had subscribed to 230.9 crore newly created equity shares at an offer price of ₹12.50 each.
The Income Tax Department subsequently sought to tax the difference between the subscription price and an assessed fair market value of ₹13.925 per share, treating the ₹1.425 difference per share as taxable income from other sources under Section 56(2)(x) of the Income-tax Act, 1961. The High Court rejected the Revenue’s approach, concluding both that the department failed to meet statutory limitation standards for reopening the assessment and that proportionate rights allotments cannot be taxed as undervalued receipts of property under the facts presented.
Legal Topic
-
Area of Law: Direct Taxation / Corporate Law
-
Sub-topic: Reassessment Jurisdiction & Deemed Income under Section 56(2)(x) / Rights Allotment
Core Legal Issue
The High Court addressed two primary legal questions:
-
Whether an assessing authority can sustain a reassessment notice when the factual foundation, calculation methodology, and legal grounds underlying the alleged income escaped from assessment are only communicated after the statutory limitation period has expired.
-
Whether an existing shareholder’s subscription to new equity shares issued on a proportionate rights basis constitutes receipt of property for "inadequate consideration" under Section 56(2)(x) of the Income-tax Act, 1961.
What Did the Court / Authority Decide?
A division bench comprising Justice B. P. Colabawalla and Justice Farhan P. Dubash quashed the reassessment notice and set aside the tax claim.
The bench held that the reopening was statutorily time-barred. Although the department issued a show-cause notice prior to the March 31 limitation cutoff, it failed to furnish the essential computation particulars, valuation methodology, and statutory justification until nearly two months after the deadline. Supplying this reasoning belatedly cannot cure a deficient notice after the limitation window closes.
On substantive legal grounds, the court held that Section 56(2)(x) does not mechanically apply to rights issue allotments. Because Grasim subscribed to rights shares proportionally and maintained the same percentage ownership without acquiring existing shares from a transferor or securing an unearned, disproportionate benefit, the price differential between the issue price and fair market value could not be treated as taxable income.
Key Legal Points
-
Procedural Limitation Cannot Be Cured Post-Facto: A reassessment notice must provide the substantive informational basis upon which the authority arrived at its belief of income escaping assessment before the limitation period expires; communicating essential calculations post-deadline cannot retrospectively validate the notice.
-
Creation vs. Transfer of Shares: An allotment of newly created shares pursuant to a rights issue possesses a distinct legal character from an inter-vivos transfer or secondary acquisition of existing shares from another person.
-
Harmonious Construction with Cost of Acquisition: Section 56(2)(x) must be read in harmony with Section 55(2)(aa), which designates the actual subscription price paid as the cost of acquisition for rights shares.
-
Absence of Disproportionate Benefit: Where a rights offering is made on a proportionate basis and does not alter the investor’s fractional interest or grant an asymmetric advantage, an allotment below market price does not constitute income under "inadequate consideration" provisions.
Relevant Law
-
Section 56(2)(x) of the Income-tax Act, 1961: Anti-abuse provision taxing the receipt of specified movable or immovable property without consideration or for inadequate consideration as "income from other sources."
-
Section 55(2)(aa) of the Income-tax Act, 1961: Defines the cost of acquisition for rights entitlements and newly allotted rights shares as the actual subscription expenditure incurred.
-
Sections 147, 148, and 148A of the Income-tax Act, 1961: Statutory framework and limitation thresholds governing reassessments and inquiries for escaped income.
Arguments of the Parties
The Petitioner (Grasim Industries Ltd.)
-
Argued that the reassessment proceedings were invalid and time-barred because the essential facts, valuation logic, and materials relied upon were not made available before the statutory limitation deadline.
-
Contended that participating in a pro-rata corporate rights offering involves subscribing to newly created equity, which does not amount to receiving property from another person for inadequate consideration under Section 56(2)(x).
-
Pointed out that its proportionate equity stake remained unchanged after the allotment, precluding any unearned enrichment or transfer of wealth.
The Respondent (Income Tax Department / Revenue)
-
Contended that the fair market value of the shares was ₹13.925 on the date of allotment, while the subscription was completed at ₹12.50 per share.
-
Maintained that the difference of ₹1.425 per share represented an unearned financial benefit aggregating to ₹329.04 crore, falling within the ambit of Section 56(2)(x).
-
Argued that issuing the initial show-cause notice within the statutory period met jurisdictional requirements, regardless of when detailed computation disclosures were subsequently provided.
Why Does It Matter?
This ruling offers significant clarity for holding companies, promoters, and corporate groups navigating capital calls and rights issues in listed entities. Corporate rights issues are routinely priced at a discount to prevailing market prices to incentivize participation; applying Section 56(2)(x) mechanically to these discounts threatened to turn routine corporate fundraisings into hefty tax liabilities.
By distinguishing between the allotment of newly created shares and secondary transfers of existing securities, the High Court’s ruling confines anti-abuse provisions to transactions that actually redistribute wealth or confer disproportionate benefits. Furthermore, the decision reinforces procedural discipline upon tax authorities, establishing that substantive reasons and computation details for reassessments must be placed on record within the statutory limitation period rather than supplemented as an afterthought.
Legal Takeaway
Subscribing to rights shares at a discount does not automatically trigger deemed gift tax under Section 56(2)(x) where the allotment is proportionate and preserves the shareholder's existing ownership ratio without conferring an asymmetric benefit. In addition, reassessment proceedings will be struck down as time-barred if the tax department fails to disclose the substantive reasons and computation basis for the demand before the statutory limitation period expires.
Sources
-
Primary Source: Judgment of the Bombay High Court in Grasim Industries Limited v. Assistant Commissioner of Income Tax & Ors. (Division Bench of Justice B. P. Colabawalla and Justice Farhan P. Dubash, decided October 22, 2026).
-
Additional Sources: Filings and corporate disclosure records relating to the Vodafone Idea Limited Rights Issue; Income-tax Act, 1961.