Navigating India’s Harmonised Wage Definition: New Labour Codes Mandate 50% Rule and Strict Compliance Timelines for Employers
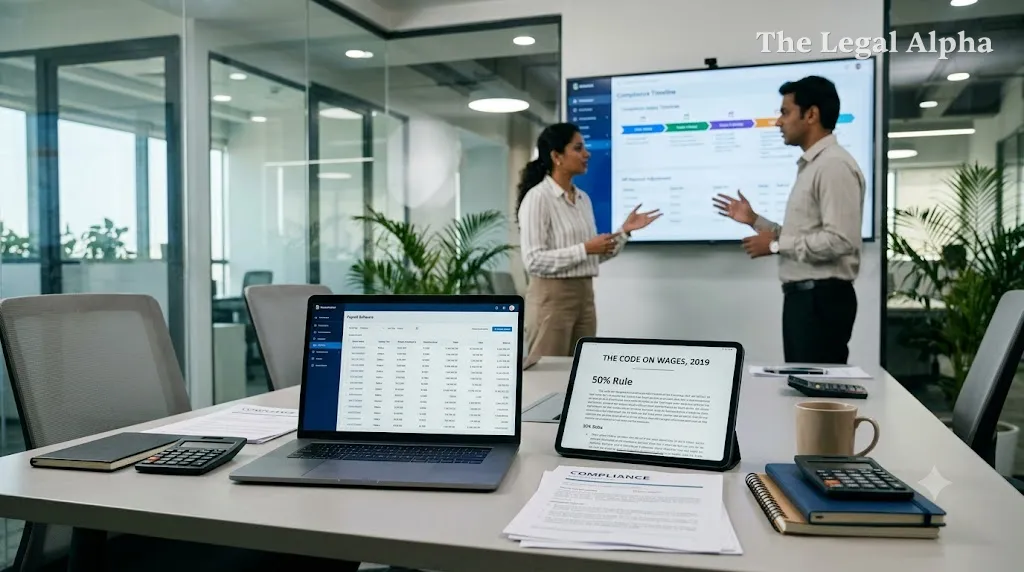
Indian establishments across sectors are overhaul-restructuring their salary architecture and statutory payout mechanisms to align with the framework established under India’s four consolidated Labour Codes. Central to this transition is the statutory definition of "wages," which limits excluded allowances to a maximum of 50 percent of total remuneration, directly influencing calculations for the Employees' Provident Fund (EPF), Employees' State Insurance (ESI), and gratuity provisions.
Alongside restructuring remuneration packages, corporate payroll departments face strict statutory timelines, including mandatory wage settlement within two working days when an employee resigns or faces termination. The transition has gained urgency as enterprises align internal compensation matrices with the Central Rules and emerging state-notified frameworks.
Legal Topic
Area of Law: Labour & Employment Law
Sub-topic: Remuneration Structuring, Social Security Liabilities & Statutory Payroll Compliance
Core Legal Issue
The core issue centres on the statutory interpretation of "wages" under Section 2(y) of the Code on Wages, 2019. Under legacy regimes, employers frequently structured compensation packages by depressing basic pay and inflating discretionary allowances (such as special allowances, travel stipends, or conveyance) to minimise statutory liabilities under the Employees' Provident Funds and Miscellaneous Provisions Act, 1952, and the Payment of Gratuity Act, 1972.
The primary question is how the statutory cap on excluded allowances applies to corporate Cost-to-Company (CTC) models, and whether non-qualifying excluded components must be re-added into the base wage for calculating social security contributions, overtime, and terminal settlements.
What Did the Court / Authority Decide?
The Ministry of Labour and Employment, through statutory rules and clarification directives, affirmed that the harmonised definition of wages must be strictly adhered to across all four consolidated Codes:
-
The 50 Percent Rule Enforced: Under the proviso to Section 2(y), if specified exclusions (such as house rent allowance, conveyance, or travel concessions) exceed 50 percent of an employee's total remuneration, the excess amount is statutorily deemed to be wages and added back to the calculation base for social security contributions.
-
Accelerated Full and Final Settlement: Under Section 17(2) of the Code on Wages, employers must disburse final wages and terminal dues within two working days of an employee's removal, dismissal, retrenchment, or resignation, replacing the earlier industry practice of 30-to-45-day clearance cycles.
-
Overtime Computation: Overtime must be remunerated at no less than twice the ordinary rate of wages, with attendance and work hours subjected to verifiable tracking under the Occupational Safety, Health and Working Conditions Code.
-
Pro-Rata Gratuity for Fixed-Term Hires: Fixed-term contract workers are entitled to pro-rata gratuity benefits upon rendering one continuous year of service, removing the conventional five-year service requirement applicable to permanent staff.
Key Legal Points
-
Uniform Base for Liabilities: Section 2(y) creates a singular definition of "wages" across the Code on Wages, the Code on Social Security, the Industrial Relations Code, and the Occupational Safety, Health and Working Conditions Code, removing fragmented definitions used in legacy acts.
-
Deemed Wage Provision: Any allowance package structured to depress the basic pay below 50 percent of total remuneration triggers statutory reclassification, automatically raising employer liability for retirement benefits.
-
Cap on Deductions: Total permissible statutory and non-statutory deductions from a worker’s monthly earnings cannot exceed 50 percent of their total wages.
-
Stricter Overtime and Working Limits: Work extending beyond standard working hours (typically eight hours daily) triggers mandatory overtime pay calculated at twice the standard wage rate.
Relevant Law
-
The Code on Wages, 2019: Section 2(y) (Definition of Wages), Section 17 (Time limit for payment of wages).
-
The Code on Social Security, 2020: Section 53 (Gratuity calculation and eligibility), Chapter III (Employees' Provident Fund framework).
-
The Occupational Safety, Health and Working Conditions Code, 2020: Working hours, spread-over rules, and overtime mandates.
-
The Industrial Relations Code, 2020: Provisions regarding fixed-term contracts and conditions of service.
Arguments of the Parties
Corporate Employers and Industry Bodies
Industry representatives have submitted that the rapid implementation of the 50 percent rule inflates statutory liabilities—notably long-term gratuity provisions and immediate cash outflows for PF contributions. Furthermore, HR and finance departments have noted that concluding all clearances, audits, and payouts within two working days of an exit creates significant operational and administrative strain, especially for large enterprises with multi-tiered clearance procedures.
Government Regulators and Labour Advocates
The Ministry and employee representatives contend that standardising wages closes historical loopholes that allowed companies to manipulate salary breakups to depress statutory retirement contributions. Proponents emphasise that while workers may experience a slight reduction in net monthly take-home pay, the reform guarantees substantial social security, higher retirement corpus accumulation, and faster dispute-free exit payouts.
Why Does It Matter?
This regulatory shift impacts virtually all formally employed staff and corporate payroll systems across India. For businesses, keeping a Cost-to-Company (CTC) neutral while increasing the basic pay component raises the actual cost of employment due to increased employer contributions to PF and higher balance sheet provisions for gratuity.
Operationally, the mandate to settle full and final exit payments within two business days requires companies to replace disjointed manual clearance workflows with integrated HRMS tools. Non-compliance also poses serious audit risks: failure to properly reclassify excluded allowances beyond the 50 percent threshold can expose enterprises to statutory arrears, interest penalties, and compounding fines during regulatory inspections.
Legal Takeaway
Under India’s Labour Codes, basic pay and retaining allowances must comprise at least half of an employee's total compensation, or the excess allowances will automatically be taxed into statutory wage calculations. Employers must audit their current salary structures to balance take-home pay and liability increases, while upgrading settlement workflows to clear terminal dues within two working days.
Sources
Primary Source:
-
The Code on Wages, 2019 (Act No. 29 of 2019), Section 2(y) & Section 17.
-
The Code on Social Security, 2020 (Act No. 36 of 2020).
-
Ministry of Labour & Employment (MoLE) Clarifications and FAQs on Labour Codes.
Additional Sources:
-
Central and State Labour Rules, Ministry of Labour & Employment notifications.
-
Statutory Compliance and Payroll Analysis Reports (CAclubindia reference review).