Washington Appeals Court Affirms Home Award Without Refinance Mandate, Finding Minimal Exposure for Ex-Husband
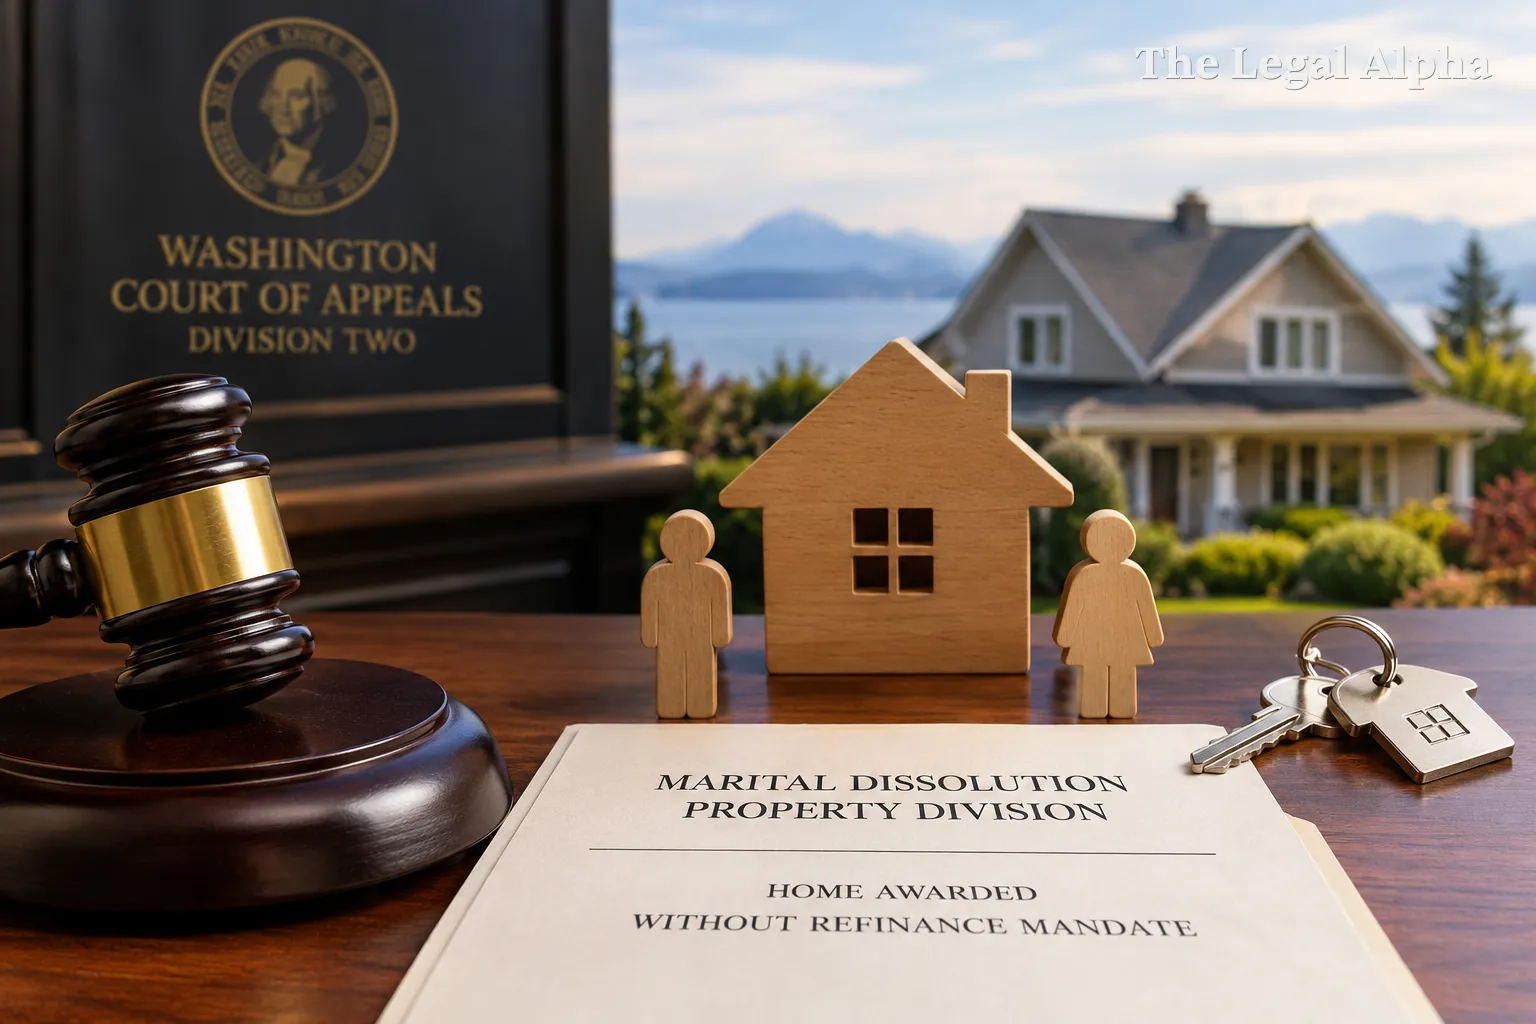
The Washington Court of Appeals (Division Two) affirmed a lower court's dissolution decree that awarded a marital home in Sequim to a wife without compelling her to refinance the existing mortgage. The former husband challenged the property distribution, asserting that allowing his name to remain on the joint loan posed significant economic exposure and left marital property unresolved. However, the appellate panel held that the trial judge acted well within statutory discretion because substantial equity in the property protected the ex-husband against foreclosure risk.
Legal Topic
-
Area of Law: Family Law / Matrimonial Law
-
Sub-topic: Marital Property Division / Mortgage Liability and Indemnification in Dissolution
Core Legal Issue
Does a trial court abuse its discretion in a marital dissolution by awarding real property to one spouse while assigning them the underlying mortgage debt, without ordering that spouse to refinance the loan to release the other from joint liability?
What Did the Court Decide?
The appellate court affirmed the trial court's property disposition. The court held that trial judges possess wide latitude under state law to fashion a "just and equitable" division of community assets and liabilities. Because the home had roughly $300,000 in equity and the divorce decree required the wife to indemnify and hold the husband harmless on the debt, the trial court reasonably determined there was little to no practical financial risk to the former husband.
The court rejected the husband's contention that the absence of a strict refinancing timeline defeated finality in property distribution, emphasizing that an indemnification obligation constitutes an enforceable final allocation.
Key Legal Points
-
Broad Trial Court Discretion: Appellate courts review property divisions in marital dissolutions under a manifest abuse of discretion standard, intervening only when a ruling is manifestly unreasonable or based on untenable grounds.
-
Equity as Protection Against Exposure: Where a residential property carries substantial positive equity, leaving a non-possessory spouse on a joint loan does not per se create unacceptable financial exposure.
-
Finality via Indemnification: A decree ordering one party to assume mortgage debt and hold the other spouse harmless establishes legal finality, even if third-party lender obligations remain unsevered.
-
No Mandatory Refinance Requirement: Washington dissolution law does not mandate an immediate refinance or property sale if the overarching distribution remains fair, just, and equitable.
Relevant Law
-
RCW 26.09.080: Washington Revised Code governing the disposition of marital property and liabilities in dissolution proceedings.
-
In re Marriage of Curtis (106 Wn. App. 191): Guiding precedent on the finality and enforcement of property division orders.
Arguments of the Parties
Appellant (Ex-Husband):
-
Argued that the trial court abused its discretion by leaving him legally bound to a major joint debt, claiming the finding of "little to no risk" was unsupported by the record.
-
Contended that failing to order an immediate refinance or date-certain sale deprived the decree of proper finality and unfairly impaired his borrowing capacity.
Respondent (Ex-Wife):
-
Maintained that the award of the home was just and equitable under the totality of the circumstances.
-
Argued that the substantial equity cushion provided adequate security against default, ensuring the husband's economic interests were safeguarded by the decree's hold-harmless provision.
Why Does It Matter?
Refinancing a marital home after a divorce has become increasingly difficult and expensive in higher-interest-rate environments. This ruling provides clarity for family law practitioners and divorcing couples who face mortgage logistics:
-
Relief for Custodial and Lower-Earning Spouses: Spouses who retain a family home are not automatically forced into forced sales or predatory high-rate refinances if the property holds sufficient protective equity.
-
Guidance on Financial Risk: The decision reinforces that "financial exposure" must be evaluated practically; significant property equity and indemnification terms can legally shield an ex-spouse even when commercial credit ties persist.
-
Judicial Flexibility: Trial judges maintain broad tools to prioritize family housing stability over immediate third-party lender disentanglement.
Legal Takeaway
A divorce court is not legally required to force a spouse to refinance the marital home to remove the other spouse from the loan. As long as the property holds adequate equity and the decree contains clear indemnification terms, judges have full discretion to allow the arrangement without committing reversible error.
Sources
-
Primary Source: In re Marriage of Mavy and Coelho, No. 60626-7-II (Wash. Ct. App. Oct. 27, 2026) (Unpublished Opinion).
-
Additional Sources: Revised Code of Washington (RCW) § 26.09.080.