Supreme Court Declines Plea Mandating Public Disclosure of Beneficial Ownership in AIFs and FPIs
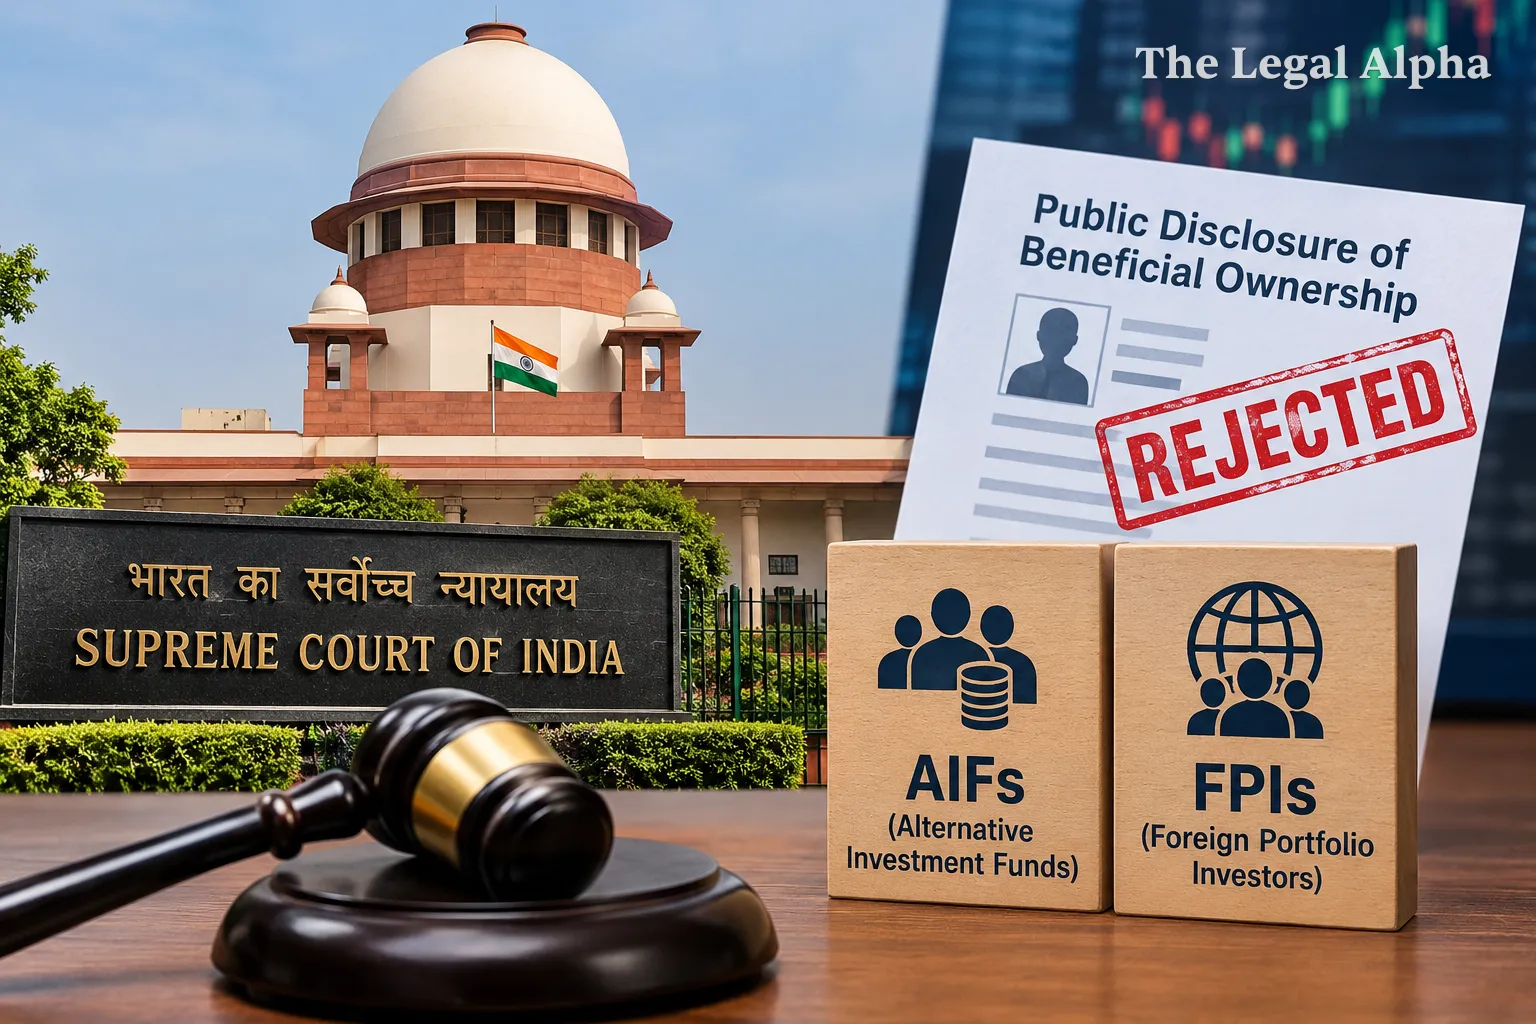
The Supreme Court of India disposed of a writ petition filed by Trinamool Congress Member of Parliament Mahua Moitra seeking directives to compel regulatory bodies to publish the ultimate beneficial ownership details and monthly portfolio holdings of Alternative Investment Funds (AIFs) and Foreign Portfolio Investors (FPIs). A three-judge Bench comprising Justices B.V. Nagarathna, R. Mahadevan, and Devendra Kumar Upadhyaya held that courts cannot venture into the sphere of economic policy formulation or issue a writ of mandamus requiring regulators to create an entirely new public disclosure framework in the absence of enabling statutory provisions.
Legal Topic
Area of Law: Securities and Capital Markets Law / Constitutional Law Sub-topic: Judicial Review of Economic Policy / Mandamus and Financial Regulatory Oversight
Core Legal Issue
The dispute centered on whether the Supreme Court, exercising its extraordinary writ jurisdiction under Article 32 of the Constitution of India, can issue a writ of mandamus directing the Union Government and the market regulator to mandate open public disclosures of ultimate beneficial owners of foreign and alternative investment funds.
The court was required to determine whether compelling such market disclosures falls within the legitimate scope of judicial intervention for retail investor protection, or whether framing disclosure norms is exclusively an executive and legislative policy domain.
What Did the Court Decide?
The Supreme Court declined to grant the reliefs sought and disposed of the writ petition.
The Bench ruled that:
-
Under Article 32, a mandamus cannot be issued to establish an entirely new regulatory mechanism where no governing statute or regulation currently mandates public exposure of such proprietary fund ownership details.
-
Formulating disclosure policies is the exclusive remit of the Union Government and the Securities and Exchange Board of India (SEBI).
-
Adequate internal regulatory safeguards already exist, as SEBI receives confidential beneficial ownership data under its supervisory powers to investigate market abuse without needing to publish those identities to the wider public.
-
The matter was left to the Union and SEBI to consider internally in light of the discussions that transpired during the hearing.
Key Legal Points
-
Limits of Article 32 in Policy Spheres: Mandamus lies to compel the enforcement of a statutory obligation or constitutional guarantee, not to order the executive or an independent regulator to draft a new economic policy or create substantive disclosure mandates.
-
Judicial Deference to Specialized Regulators: Courts exercise restraint in matters governing complex financial architectures, acknowledging that securities market transparency norms involve balancing investor protection with market stability and capital inflows.
-
Distinction Between Regulatory Access and Public Disclosure: The bench differentiated between regulatory supervision—where SEBI can demand and review underlying ownership data—and broad public dissemination of sensitive investor information.
-
Investor Autonomy: The court rejected the generalized presumption that retail investors are uniformly defenseless, observing that participants in contemporary capital markets have access to professional advice and research.
Relevant Law
-
Article 32 of the Constitution of India: Remedies for the enforcement of fundamental rights and the parameters governing the issuance of prerogative writs.
-
Securities and Exchange Board of India Act, 1992: Sections governing the regulatory ambit of SEBI to monitor unfair trade practices and regulate market intermediaries.
-
SEBI (Foreign Portfolio Investors) Regulations, 2019: Regulatory framework controlling the registration and supervisory compliance of foreign entities investing in Indian securities.
-
SEBI (Alternative Investment Funds) Regulations, 2012: Framework governing privately pooled domestic and global investment funds.
Arguments of the Parties
Petitioner Appearing for the petitioner, Advocate Prashant Bhushan argued that AIFs and FPIs control over ₹100 lakh crore—representing more than 20 percent of India's aggregate stock market capitalisation. He submitted that retail investors are placed at severe information asymmetry, exposing them to artificial share price inflation, circular trading, round-tripping, and market manipulation. The petitioner asserted that citizens' and investors' right to know who is driving market volumes must override investor privacy, urging the court to intervene as it had done in earlier transparency-related public interest litigations.
Respondent / Union of India Solicitor General Tushar Mehta, appearing for the respondents, submitted that judicially mandating unrestricted public disclosure of ultimate beneficial ownership across international funds would destabilize the national economy and trigger significant capital flight. He contended that securities regulators across major economies maintain confidential registries rather than unfettered public disclosures, emphasizing that SEBI already holds extensive statutory powers to access ownership trails whenever surveillance triggers an inquiry.
Why Does It Matter?
This ruling reaffirms the Supreme Court's adherence to the doctrine of separation of powers in capital markets regulation. For global institutional funds and private equity managers, the decision averts immediate structural disruption by keeping beneficial ownership reporting confined to regulatory reporting rather than general public registries. It signals to foreign portfolio investors that judicial intervention will not bypass existing statutory boundaries to impose ad-hoc transparency regimes. At the same time, the proceedings underscore the scrutiny surrounding opaque fund layers, placing the ball squarely in SEBI's court to adjust risk-based disclosure guidelines as cross-border inflows expand.
Legal Takeaway
The Supreme Court has reiterated that judicial review under Article 32 cannot be used to bridge statutory gaps or compel regulators to enact commercial policy regimes. In financial markets, determining the balance between confidential regulatory supervision and mandatory public transparency remains the exclusive prerogative of the legislature and SEBI.
Sources
-
Primary Source: Supreme Court of India, Mahua Moitra v. Union of India & Anr., Writ Petition (Civil) No. 885 of 2025 (Order dated October 29, 2026; Bench of Justices B.V. Nagarathna, R. Mahadevan, and Devendra Kumar Upadhyaya).
-
Additional Sources: Filings and proceedings reported via Bar and Bench, LiveLaw, and The Economic Times.